Showing posts with label Miners. Show all posts

Saturday, January 04, 2014

Adam Hamilton: Silver Short Squeeze SLV, MUX, TNR.v, GDX


  Adam Hamilton presents his outlook on the recent situation in Silver market. Gold and Silver have very strong start in 2014 recovering from the testing of Double Bottom in 2013 on the new money allocated to the sector. If next week this dynamic will continue we can have the very explosive situation as it happen in summer 2013 with Silver skyrocketing towards 25 mark. Junior miners should participate in this fireworks again like it happen with McEwen Mining and TNR Gold before, which we are following here. The chart above from KWN demonstrates that Silver is now extremely oversold.


Rob McEwen: “The Next Run Will Be Driven By Gold Moving Higher, As Well As New Discoveries” MUX, TNR.v, GDX, GLD

 "Rob McEwen gives his view on the Gold market and what will be the driving force behind the next Bull Run. He is looking for the deals in this market environment and that new discoveries will be driving the successful companies backing them. Meanwhile Gold is under pressure today testing the recent lows. Equity markets are drifting lower and Interest Rates higher. Rob reminds us, that turnaround can be very fast as we saw this summer after Gold has bottomed out and miners were spiking up. Equity markets are very high now and Gold sector is very undervalued, people will start looking at the relative values at these levels."

Adam Hamilton:

Adam Hamilton     January 3, 2014     2799 Words

Silver is poised for a massive recovery upleg in 2014, a mean reversion from last year’s dismal action.  The main driver of silver’s initial strength will be American futures speculators covering shorts.  These bearish bets on silver soared to a bull-record high last month, which will require exceptional buying to unwind.  Futures speculators as a herd always bet wrong at major lows, they are a fantastic contrarian indicator.

Because futures trading is such a hyper-leveraged zero-sum game, futures traders have a reputation of being smart and sophisticated.  And they are to a great extent, futures are so unforgiving that survival of the fittest rules.  Capital naturally flows from the poor traders to the good ones.  Nevertheless, within their chests thump the same hopelessly emotional human hearts that are such a liability in the markets.

Even good futures traders succumb to groupthink, getting too greedy or too scared with the rest of the herd.  They flood into silver futures after the metal has already surged in strong uplegs, buying into the popular euphoria.  Then they flee silver after it has plunged, waxing bearish with everyone else.  This leads to buying high and selling low, the same emotional affliction that torments nearly every trader.

Futures trading is one of the purest forms of speculation, making leveraged up-or-down directional bets on underlying prices.  When these traders buy silver futures, they expect its price to rise imminently so they are effectively bullish on the metal.  When they sell, they expect silver to fall in the near future so they are bearish.  Thus looking at their aggregate bets on silver reveals their collective sentiment on it.

Thankfully this useful data is readily available.  All silver futures buying and selling gets distilled into the famous Commitments of Traders reports from the US Commodity Futures Trading Commission.  These weekly reports show how futures speculators as a group are betting on silver.  They’ve always been the most bearish, as evidenced by the most selling, right when silver happens to be carving major bottoms.

Futures are a zero-sum game, every contract has a trader on the long side betting a price will rise and an opposing trader on the short side betting that same price will fall.  Every dollar won by one trader is a direct dollar lost by the trader on the other side of that contract.  The total number of longs and shorts in silver futures always nets to zero.  But the classic CoT reports divide traders into three separate groups.

They are commonly known as commercial hedgers, large speculators, and small speculators.  Of course the first group actually produces or consumes physical silver for business purposes.  They are simply trying to lock in future prices to better manage their cashflows.  The latter two groups of speculators take the opposing side of those hedging trades, and it is their bets that are a powerful contrarian indicator.

This first chart looks at the net-long and net-short positions among these broad categories of traders.  The more net-long silver-futures speculators get, the more bullish they are on silver’s price.  But the opposite extreme is far more interesting today.  The less net-long or even net-short speculators become on silver, the more bearish they are on it.  And in recent weeks that bearishness has approached record extremes.
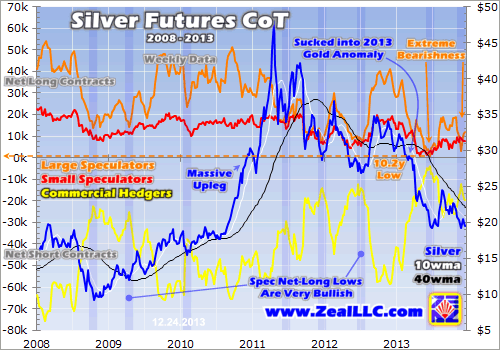

Recently in early December as silver slumped back towards its brutal June lows, futures speculators’ net-long positions plunged.  The large specs’ net-long futures contracts held fell to just 2.9k.  How low is that?  Between 2009 and 2012 before last year’s epic precious-metals selling anomaly, large specs averaged net-long positions of 28.1k contracts.  A month ago they were merely 1/10th normal levels.

Silver’s secular bull was born way back in November 2001 just above $4 per ounce.  Since then there have been 631 weekly CoT reports.  Large specs’ net-long positions have fallen under 3.0k contracts on just 10 of those, or 1.6% of the time.  2 of those weeks were last year, the first in late June.  When futures speculators as a herd get that bearish on silver, the white metal is always on the verge of a major surge.

Right after that late-June episode of exceptionally-low speculators’ net-long positions, silver soared by nearly a third in the next couple months.  Right when futures speculators were the most bearish on this metal as evidenced by their low net-long positions, it was bottoming.  They were betting against silver at exactly the wrong time, selling low.  And this certainly wasn’t the first time, specs have always done this.

Late June’s large-spec net-long contracts happened to fall to their lowest level in just over a decade, truly anomalous.  But in general spec net-long lows are very bullish silver indicators even when they aren’t as extreme.  A basic rule of thumb is that if spec net longs are near their lowest levels in at least 6 months, they reveal excessive bearishness.  And that has always been a universal contrarian indicator.

I highlighted some of these episodes above in blue.  Pretty much without exception, when large futures speculators’ net-bullish bets on silver reach a major low, this metal is also at a major low.  Note above how the large-spec net-long lows coincide with bottomings in silver.  Immediately after these speculators wax the most bearish, silver starts powering higher in either a sharp rally or a much longer major upleg.

While there are some very smart silver-futures traders out there, as a herd they succumb to popular greed and fear just like the rest of traders.  They get too bullish after silver has already run too high too fast, and too bearish after silver has already fallen too low too fast.  They trade like momentum players, betting that whatever mature trend is in place will continue indefinitely.  But that really isn’t prudent.

Universally in the financial markets, greed and fear dominate short-term price action.  Once greed crests after a long upleg, everyone who is interested in buying in anytime soon has already bought.  That leaves only sellers, so the price soon corrects.  And once fear peaks after a deep correction, everyone who is susceptible to being scared into selling has already sold.  That leaves only buyers, so the price rallies.

Excessive greed and fear naturally burn themselves out, spawning all the major trend changes.  These are exceedingly profitable to trade if you can get in fairly early near the inflection points.  Contrarian traders attempt to do this, buying low when everyone else wants to sell then later selling high when everyone else wants to buy.  Being brave when others are afraid is the only way to consistently buy low.

But fighting the crowd is never easy, because your own heart will desperately try to convince you to wrongly be excited or scared exactly when everyone else is.  You can short-circuit that desire with context data like silver-futures specs’ net positions that reveals when everyone else is too bullish or bearish.  And with net longs not far above decade-plus lows in recent weeks, specs’ bearishness remains extreme.

And provocatively this very bearishness in futures is what drives the initial silver rallies out of net-long lows.  Futures enable traders to easily sell silver short, to effectively borrow silver they don’t own and sell it in the open market.  If the silver price soon falls as these short sellers expect, they can then buy back the silver they originally borrowed at a lower price to pay it back.  Then they pocket the difference as profit.

When a price is falling particularly sharply, and fear is exceptionally high, short sellers are often the only buyers around.  Their buying to cover slows the price decline, reverses it, and then accelerates it back to the upside.  The higher the short positions, the larger the necessary buying and the bigger these short-covering rallies become.  And last month total spec silver shorts surged to a record, a super-bullish omen.

This next chart slices up the weekly CoT data a bit differently, adding the total long-side and short-side silver contracts that both large and small speculators hold.  Every silver contract sold short has to be bought back before it expires, creating futures buying demand.  And when silver starts rallying in the face of large short positions, the traders have to scramble to cover before their leverage slaughters them.
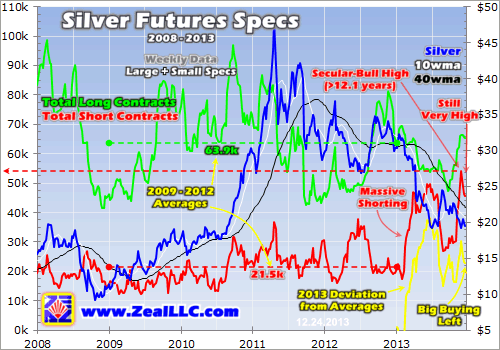

Just a month ago in early December, the total silver-futures short positions held by both large and small speculators surged to 54.3k contracts.  This is astoundingly high, actually the highest levels ever seen in silver’s entire dozen-plus-year secular bull!  It is also over 2.5x the 2009-to-2012 average levels seen before 2013’s wildly anomalous selling.  And these shorts haven’t come down much in recent weeks.

The speculators holding these massive shorts have no choice, they have to buy long-side contracts to offset their shorts and cover them.  And this has to happen before expiration, which is in the next couple months for most of the outstanding contracts.  But if silver starts rallying sharply, these speculators will have to buy very quickly to limit their leveraged losses.  This should ignite a major short-covering rally.

Each silver futures contract controls 5000 ounces of silver.  At $20 per ounce, that is worth $100k.  Yet futures speculators are only required to put down an initial margin of $11k to buy a single contract, and the maintenance margin to keep that position is only $10k.  So silver-futures speculators can effectively run 10-to-1 leverage today.  That dwarfs the 2-to-1 legal limit for stock trading that’s been in place since 1974.

While futures speculators don’t typically run maximum leverage, they like to get close since that is the main allure of futures trading.  They can win huge gains on their capital risked with relatively small moves in the underlying commodity’s price.  But when that moves against them, the losses snowball just as fast.  And at or near 10x leverage, there is very little room for error in the enormous silver shorts.

As all silver investors know, silver has always been an exceptionally-volatile metal.  3%+ price moves in a single trading day aren’t uncommon at all.  For silver speculators shorting at minimum margin (maximum leverage), silver merely rallying 10% wipes out 100% of the capital they risked!  And if silver keeps rallying, which is very likely once momentum shifts in its favor, they can lose far more than they initially bet.

And the greater speculators’ total short positions, the greater the risk they all face of a really big and fast rally erupting to wipe them out.  Once again the only way to close these shorts is to buy futures to offset them.  So as soon as a small fraction of speculators start buying to cover, silver’s price starts rising.  That convinces increasingly bigger fractions of the remaining traders to buy to cover, sparking a self-feeding cycle.

The more shorts who buy futures to cover, the faster silver’s price rises.  And the faster silver’s price rallies, the more pressure it puts on the remaining short speculators to close their positions.  That is why it is so exceedingly dangerous to be short when everyone else is.  Short covering can quickly become a stampede for the exits, with very few speculators getting out unscathed.  Their frantic buying creates a short squeeze.

While some minor short covering happened in December after that secular-bull-record short position of the futures traders, their shorts remain very high.  As of the latest CoT report (Christmas Eve), they still had 45.5k contracts short!  In the 631-CoT-week history of silver’s secular bull, only 16 weeks saw spec shorts over 45k contracts.  Fully 15 of those happened during 2013’s wildly-anomalous silver selloff.

After shorting extremes, positions quickly mean revert back to averages.  Between 2009 and 2012 in normal years for silver futures trading before 2013’s anomaly, speculator short positions averaged 21.5k contracts.  That means traders are going to soon have to buy to cover 24.0k merely to mean revert, not even to overshoot as usually happens after extremes.  And that is a lot of silver buying likely to happen quickly!

At 5000 ounces per contract, this mean-reversion silver buying from short-side silver-futures speculators alone is 120.2m ounces!  Both the US Geological Survey and the Silver Institute estimate total global mine production in 2012 around 780m ounces.  So the short covering necessary by American futures traders merely to return to recent years’ average levels of shorts is nearly 1/6th of total worldwide production!

And because of the risks rapidly-rising prices pose to short sellers’ capital, short covering happens fast.  So once this mean reversion starts, all this silver is very likely to be purchased in the US futures markets alone within a couple months.  You can see how fast speculators’ short positions dropped after past extremes in this chart.  Once short covering starts, it rarely stops until positions fully mean revert or overshoot.

Today’s near-record futures shorts are extremely bullish for silver as we dive into 2014.  It is guaranteed near-future buying that feeds on itself.  The early gains in major new silver uplegs are nearly always sparked by short covering, and the bigger the shorts the greater the initial boost.  But futures speculators short silver are certainly not its only buyers.  Their early buying will start enticing investors back into silver.

As I explained in an essay a couple weeks ago, silver has many exceptionally-bullish factors going for it in addition to the extreme futures shorting.  It has converged on multiple major secular support zones, atechnical launchpad from which past major uplegs were born.  Silver also remains very cheap relative to its primary driver, the price of gold.  Once silver starts rallying decisively, investors will start flocking back.

A silver short squeeze will spread like a wildfire in a bone-dry forest.  Despite silver’s miserable 2013, its ages-old allure certainly wasn’t stamped out.  Great latent interest in silver remains among investors and speculators alike.  Though silver plummeted 36% last year thanks to gold’s anomalous selloff dragging it down, the holdings of the flagship SLV silver ETF only fell 1%.  And physical silver demand soared worldwide.

So as silver starts rallying again initially on short covering, it will ignite widespread buying from all quarters.  This will feed on itself too.  The more capital that returns to silver, the faster its price will rise.  And the quicker it rallies, the more investors it will attract in.  The gains in silver this year ought to be enormous, well over 50% as I explained a couple weeks ago.  But the silver-stock gains will dwarf those.

The stocks of silver miners and explorers were thrashed to within an inch of their lives in last year’s precious-metals carnage.  They’ve never been more undervalued relative to silver even near its recent lows, truly atfundamentally-absurd levels.  So as silver recovers this year, silver stocks are overdue to see gigantic mean-reversion gains.  Most should at least quadruple, with the best flying even higher.

At Zeal we’ve been intensely studying silver stocks for over a decade.  Very fortuitously considering the epic silver-stock bargains out there, we recently finished our latest 3-month deep-research project looking into silver stocks.  We started with a universe of nearly 120 of them trading in the US and Canada, and gradually whittled them down to our dozen fundamental favorites.  These winners are awesome.

They have been able to thrive operationally even in 2013’s extreme carnage, and will enjoy vast upside leverage as silver recovers.  All dozen are profiled in depth in our fascinating new 27-page silver-stock reportrecently published.  We are offering these fruits of hundreds of hours of expert world-class research for just $95, a steal.  Buy your report today while silver stocks are still cheap!  That window will rapidly close.

We also publish acclaimed weekly and monthly subscription newsletters.  They offer a priceless and rare contrarian perspective cultivated from our decades of hard-won experience, knowledge, wisdom, and ongoing research.  I explain what is going on in the markets, why, and how to trade it with specific stock trades.  2014 will look very different from 2013, so subscribe today and start preparing for big changes!

The bottom line is silver is on the verge of a massive short squeeze.  Speculators’ silver-futures shorts surged to extreme bull-record levels less than a month ago.  And they’ve barely started to mean revert, which means big buying to cover is still coming soon.  While speculators’ silver-futures positions are always a great contrarian indicator at extremes, exceptional shorts are the most bullish portent of all.

Unlike new long-side buying, short covering isn’t optional.  Silver futures’ hyper-leverage guarantees that speculators have to quickly buy to cover as silver’s price rises.  This feeds on itself, igniting a buying frenzy as traders rush for the exits.  The bigger their aggregate shorts, the greater the rally their covering sparks.  So the recent bull-record shorts are a super-bullish harbinger for silver and its miners’ stocks.

Adam Hamilton, CPA     January 3, 2014 "

Enhanced by Zemanta

Saturday, September 21, 2013

Eric Sprott: "China Bought 60% of Gold Production Last Month, I Am Buying Gold And Silver Stocks Now." MUX, TNR.v


  Marin Katusa is asking Eric Sprott really straight forward and tough questions in this interview. The last two years were very brutal for any Gold and Silver investors, and Eric Sprott - with his huge exposure to Silver after its Crash from $50 - was not having the best of his time for sure. The most important question for everybody involved now is what will happen next. 
  Price of Gold and Silver will be the main driving forces for all survived companies. Eric has very bold prediction for Gold going to $2400 by next year: "The most important thing in the precious metals business - the price of precious metals. They all go up if the price of Gold will go up. The question is which one will go up 200% or 500%. If the Gold will go up to $2400, I can bet that the Gold miners index goes up 200%. What we are trying to do: where is the one which will go up 1000%."
  This summer we had the capitulation in Gold and Silver stocks with the following turn around and now we are looking to the Eric Sprott and Rick Rule for guidance to run this new Bull. China will play the very important role in this big picture, according to Eric.

Rick Rule On Gold & Resources: "The Stage Is Set For An Absolutely Dramatic Recovery" TNR.v, MUX

"This is why it is called capitulation and this is how the trend is changed and this is when the new Bull is born. Apart from all emotions and pure market manipulations, the share price is determined by supply and demand in the market place. The last sellers in the Bear market are the funds with redemptions, which are closing their shops and liquidating anything at ANY price they can find and the last Believers, who can not handle it any more and are throwing into the towel."


MineWeb: Jumping Chinese gold imports on pace to 1,000 tonnes GLD, GDX, GDXJ, MUX, TNR.v


 "Gold is under attack today and next week we will find out the amount of tapering. During the brutal gyrations in the market place it is important to keep the big picture in front of you. We will share a few pieces today, which shows who is doing what behind the noise."

Enhanced by Zemanta

Saturday, February 16, 2013

CITI: Gold Has Fallen To A Pivot Point, Minimum Price Target Now $2,055


 C.S. It is the time of total desperation in Gold Miners and, particularly, Junior Miners these days. Investors are questioning this Bull and are throwing the babies with the bath water all over again. Time is to look at the charts and to rub our Crystal ball.

Frank Holmes: Follow The Money - Warren Buffett vs. Gold


  "Frank Holmes has presented the beautiful deck on Global Trends and the place of Gold in this day and age. Please notice the recent average grades of producing Gold mines and the scarcity of the new discoveries with the magnitude of 3 MOZ and more."


Business Insider:

CITI: Gold Has Fallen To A Pivot Point, Minimum Price Target Now $2,055


Gold fellow below $1,600 on Friday.  This is a six-month low.

According to Citi technician Tom Fitzpatrick, this is exactly where you want it to be if you're a gold bull.

Eric King of King World News has a clip from Fitzpatrick's latest note.

“We believe we have just reached the ideal pivot for gold to form a base and move higher as it did after the 16 month consolidation in 2006-2007," wrote Fitzpatrick who now has a “...a minimum (price) target of $2,055-$2,060.”


  First of all, our December Call on Apple: timing was perfect this time - it was a very powerful formation. There is still room to fill to 400, prudent way will be to take profit now and run 30% of the Short position Down to the target. Too many people are selling Apple now and Gold provides much more lucrative proposition as per below.

Apple To Break Down to 400 and Gold & Commodities To Break Out on China Move AAPL, GLD, FXI, TNR.v, ILC.v, LMR.v, RM.v, CZX.v


  US Dollar is still in the same H&S reversal formation, nothing has changed with all Currency War talks, US Debt is still there and the only way out is to debase the US Dollar.


  We like what we see on on the Long Term Gold chart from CITI. The chart above is not so apparent, but provides support to the same idea. After previous Bull Leg Up Gold is in the consolidation pattern and has created two Bullish wedges. Last week sell off "coincided" with Currency Wars talks among G20 and some help from JP Morgan selling heavily all the week. Soros has announced that he has reduced his holdings in GLD, but we trust more the Gold appetite from China and Russia buying in increasing volumes alongside with other Central Banks. And who knows, maybe, Soros is just switching to the Physical from the Gold ETF among other players.
  Next week Chinese will return from the holidays and it will be interesting to see the direction in Gold. We are in transition stage now from Gold as Insurance Play to the Inflation Play. The real driver for the Gold price is increasing monetary base, debasing of the currencies and negative Real rates. Our best gains in Gold and, particularly, Gold Equities we had after 2002, when economy was "recovering" and FED was solidly behind the interest Curve.
   Now we have all fundamentals in place for another Gold Bull Leg Up to start and, according, to CITI this coiled market is ready to move very soon. The very strong technical support is at 1550 and Gold should bounce of it in this scenario forming the strong Reversal Candle on weekly, still missing in the picture.


  Gold Miners are at the very important pivotal point as well. Should the Gold find itself in the new Leg Up - they will follow. Even more importantly, they must confirm the Gold's move. We have the right set up for this action now. Last few weeks sell off was particularly brutal and we can talk about the Capitulation in this market. We can have the double Bottom reversal on Monthly chart, which will be very strong formation.
 Gold Majors are suffering: despite strong Gold prices companies are experiencing margin compressions with cost even outrunning the Gold price run. New projects are late on time and over the budgets, massive writes off, from the previous expansion phase were the main news in the latest reports. All these developments will support the price of Gold marching Up again.
  Here is where we can see the Main Investment Theme: M&A in search for the ever decreasing Gold Reserves in Stable Mining Jurisdictions. It will be safe to say that you can forget about any Gold production in Russia and China - all that gold will be accumulated within those countries. Africa is losing its battle being caught between geopolitical interests in the War for Oil. Canada and North America and, particularly, Alaska will attract new wave of consolidation among juniors providing the pipeline of projects for the majors.


  The next main action in the Gold market will be among Junior Miners. If Majors are depressed by now, Juniors have been just slaughtered. We can see the same capitulation on the chart above, as with GDX before. 
  Problem here will be that maybe 80% of this market will be gone for good in consolidation and bankruptcies. It will be very selective game from now on. Only Special Situations will bring the serious money. Assets, Teams and Access to the capital will be the prerequisites for the lead in this game, as usual.


  The Chart above is the driver for the Gold Inflation Play. Once the world will stop to worry about its own end, China's Growth will be the main driver for Gold. This picture is still intact after our Apple observations in December.


  As Jim Rogers has suggested: "Do what you know the best". We will paraphrase: invest in what you know the best. Here where McEwen Mining comes into the picture. Even Mr GoldCorp - Rob McEwen was not spared by the brutal Mr Market. After acquisition of Minera Andes by US Gold with combined market caps of over 2 billion dollars in the first half of 2011, when the "merger" has been announced - McEwen Mining was trading last Friday at roughly 796 million (296 million Common and Exchangeable Shares at 2.69).
  We have been investing in Minera Andes years ago at 0.40CAD and we were fortunate to sell it at its run to over 2.0CAD in 2007. Later we have revisited this story with TNR Gold and its Claims to Los Azules. There were very heated discussions among Minera Andes shareholders about the price paid for their company. Only the future will tell whether Minera Andes' assets will still allow Rob McEwen dream about S&P 500 to happen or they have just brought the curse from Argentina to his new company.
  It was a tough road for McEwen Mining shareholders. So far, only Allen Ambrose, former CEO of Minera Andes, was "lucky" with his timing to sell 1.7 million worth of shares of McEwen Mining straight after the merger at the levels higher than 6 dollars in 2012. After that MUX was hit with "news about Argentina" in spring of the last year and later in November McEwen Mining has settled litigation with TNR Gold reinstating TNR Gold's Back-In Right to the Northern Part of Los Azules and issuing 1 million shares of MUX to the junior.
  Fragile market confidence was not helped by the Rights Offering at 50% discount at the moment of announcing in October 2012 - at 2.25 dollars. Trade was quite obvious and Shorts were selling MUX at market, planning to cover by buying the Rights, which were trading on the market as well. This is where we find McEwen Mining at the moment of writing - with 2.69 at Friday's close company is just 20% above the Rights Offering price. Its market cap is far cry from the needed 4 billion dollars in order to qualify for S&P inclusion in 2015, company needs at least 120 million for the El Galo expansion and another Rights Offering can easily bring it below 2 dollars. Market knows it and punishes McEwen Mining with the rest of the Gold market as we have discussed above.
  Should we write off Rob McEwen and his Midas touch? Contrary, we would say that it could be the most intriguing story in the making in our turn-around Gold juniors. All those bad news and developments are already in the market. Short position in MUX has been at 29 million shares as of the end of January. Company has reported spectacular results from Los Azules and announced the expansion of the resources. BMO was hired to market the "One of the World's  largest undeveloped copper project". According to Rob's facebook page, last week McEwen Mining had meetings in Toronto presenting Los Azules developments. Barrick Gold's Pascua Lama was reportedly cleared from "Rock Glaciers" investigations and has received the support of San Juan government in Argentina. McEwen Mining with Los Azules is being reviewed this month.
  Here where Rob McEwen will be coming at his prime as promoter - running against the clock for his goal to qualify for S&P 500 by 2015 he has the last opportunity to turn this story around. 70 million in cash will not buy the place in S&P 500 by itself or even the Second Stage at El Galo, but it will be enough for the "Chief Owner" to fight for his company. Research valuations of McEwen Mining, including the Los Azules valuation will draw the market attention and any hint about the potential buyers for this world class copper asset can make Shorts rushing to cover. 
  Watch out the retest of 2.25 and developments around Los Azules - it will be the key to McEwen Mining performance.
  On our part we will continue to follow TNR Gold as a Call Option on Los Azules without The Time Decay and monitoring its Shotgun Gold project development in Alaska.


Please Note our New Legal Disclaimer on the Blog, including, but Not limited to:

There are NO Qualified Persons among the authors of this blog as it is defined by NI 43-101, we were NOT able to verify and check any provided information in the articles, news releases or on the links embedded on this blog; you must NOT rely in any sense on any of this information in order to make any resource or value calculation, or attribute any particular value or Price Target to any discussed securities.


We Do Not own any content in the third parties' articles, news releases, videos or on the links embedded on this blog; any opinions - including, but not limited to the resource estimations, valuations, target prices and particular recommendations on any securities expressed there - are subject to the disclosure provided by those third parties and are NOT verified, approved or endorsed by the authors of this blog in any way.


Please, do not forget, that we own stocks we are writing about and have position in these companies. We are not providing any investment advice on this blog and there is no solicitation to buy or sell any particular company.

Enhanced by Zemanta

Tuesday, July 24, 2012

MineWeb: Commodities bull Mills particularly likes prospects for gold, silver and uranium


EXCLUSIVE - Bill Murphy's London Source: "Big Gold & Silver Moves Coming in August"

"Looks like a lot of things are happening behind the closed doors of the major banks these days. Reuters is talking today about arrests coming in Libor case and we guess that some traders will be thrown out from Bullion Banks once Gold and Silver manipulation news hits the headlines. Naked Short Selling in Gold, Silver and in junior miners will be next to surface and short covering should be very dramatic in its violent move."


Gold Manipulation: London Trader - The LBMA Gold Price Fixing Scheme Is Over

More and more news about manipulations of the different markets is coming to the surface now. It is too wide spread to conceal it any more. All markets are rigged: LIBOR, Gold, Silver - PPT is holding the market's breath every time at the crucial technical points. Crime of the century - Naked Short Selling will be next to finally turn this scam to the light of day. Goldman Sachs has managed to get to the front row in this dirty game as well."


MineWeb:


Commodities bull Mills particularly likes prospects for gold, silver and uranium

Equity valuations have so far failed to keep pace with rising bullion prices, but that makes for some outstanding investor opportunities among a few particularly well-positioned juniors. Rick Mills is interviewed by The Gold Report.


Author: Sally Lowder
Posted: Monday , 23 Jul 2012 
COQUITLAM, BC - 
The Gold Report: Prices of the mining equities were languishing when we spoke in January, particularly precious metals equities, and we've had little respite since then. But you foresee potential for a bullish resurgence in gold equities. What's your rationale behind that outlook?
Rick Mills: I believe we're going to see higher levels of inflation. We're going through a deflationary bout now because most of the money issued by the Federal Reserve is actually parked at the Fed. It isn't out there being spent, so it's not causing inflation. It's basically just propping up the banks. When the banks start lending and when the money gets into circulation, we'll see increased levels of inflation and, of course, that will be good for gold.
TGR: Lack of access to capital for small business due to stringent credit requirements is one factor that has put a damper on the economy. What will prompt banks to ease up on credit standards?
RM: I'm probably going to stir up a little bit of controversy by saying so, but I firmly believe that the way out of the dilemma we're in is to spend more money. A lot of people don't agree. They think we should cut back on spending, raise taxes and go onto an austerity program. That is absolutely the wrong thing to do. Taxes should be reduced. I believe they should be spending a lot more money.
TGR: Who should be spending more money?
RM: World governments should implement massive global infrastructure maintenance and build-out programs, and put the money not into the banks but into the small businesses that will build the infrastructure. These small businesses are the ones responsible for most of the job creation. So, give the money directly to the small businesses. Hire them to do this infrastructure build.
Take a look at our global water supply problems, our highways, our bridges, the brownouts because our hydroelectric power corridors are so outdated, the switching stations literally melt when they overload. We can actually spend our way out of this. In a fiat currency regime, because nothing is anchored to gold, the only way to move forward is to keep spending money. We saw this when the U.S. Quantitative Easing Two stopped and the lack of liquidity immediately upset the markets. If we undertake the infrastructure build-out program and give the money to the small businesses that create jobs, as people get back to work, they'll have money, spend it and revive the economy. And it's not only the U.S.-every country in the world has an infrastructure deficit.
TGR: What would more capital distribution among small business mean for the price of precious metals?
RM: The moderate to high levels of inflation I anticipate will make gold a much more attractive asset. The banks will keep interest rates low to help stimulate business borrowing, and with low rates, typically below 2%, you've got higher rates of inflation than you are getting for interest. I wrote an article called "Six Percent Can Draw Gold from the Moon." With high levels of real returns people don't favor gold as an investment. But when rates are below 2%, the exact opposite happens, because the real rate of return is negative. For instance, if investors are getting 2% on bonds but the real rate of inflation is running at 3-3.5%, they actually lose purchase power because the real rate of return is negative 1-1.5%. So higher inflation just makes gold all that more attractive. It preserves purchasing power and, of course, the gold price is going up at the same time.
TGR: As we speak today, gold is up $25/ounce (oz), flirting with $1,600/oz. Given that-and the fact that gold is not only a store of value but also a hedge against inflation-where do you predict the gold price will go during the rest of the summer and into the fall?
RM: I honestly don't have a price prediction except that gold will go higher. When we talked last year, I was perfectly comfortable with $1,500/oz gold and thought that was a good price for it. Of course, it immediately spiked up to $1,900/oz but has come back to my range. I'm still perfectly happy with $1,500/oz gold. As more people catch on to the fact that they need to own some gold, the price will slowly rise.
TGR: Some people believe one of the reasons gold will go higher is because of the whispers we're hearing that the Bank for International Settlements (BIS) intends to reclassify gold as a risk-free asset in the context of the Basel III framework. Could you help our readers understand why that would be bullish for gold?
RM: Tier 1 capital is the core measure that regulators use to gauge a bank's financial strength. It typically consists mostly of common stock and disclosed reserves or retained earnings but it might also include non-redeemable, non-cumulative preferred stocks. The Basel Committee for Bank Supervision, known as the BCBS, which is the maker of the global capital requirements, also implemented the Basel III rules that form the basis for global bank regulation. The BCBS is studying makinggold a bank capital Tier 1 asset. Gold has typically been a Tier 3 asset, which means that it's been discounted at 50% of its current market value. With that discount, banks really never had reason to hold gold as an asset. If the BCBS raises gold to the level of a Tier 1 capital asset, though, banks could operate with far less equity capital than is normally required and gold would be the ultimate backstop for debt, currencies and bank equity capital. It would be a huge move, and making it would really propel some superior interest in gold.
TGR: Certain central banks, such as China's, are stockpiling gold already. If it becomes a zero-risk-weighted Tier 1 asset, countries all over the planet would start accumulating gold, which would of course drive up demand. What's the timeline on the BCBS decision?
RM: We simply don't know. But if it happens, you're going to see substantial demand for physical bullion and it's going to be a hugely important step toward gold's re-monetization. Moving from a Tier 3 to a Tier 1 asset would have gold compete directly as a safe-haven investment against bonds issued by over-indebted governments and yielding less than zero in inflation-adjusted terms-those negative real interest rates we discussed.
Another factor to bear in mind, one that isn't widely recognized, is that there is a huge shortage of good collateral; banks are increasingly accepting gold as collateral because they're reluctant to take each other's fiat currencies. So there's another huge step toward the re-monetization of gold.
TGR: That would certainly suggest increasing value for the shares of companies searching for and producing gold. Some of them are producing gold very profitably at well under $1,500/oz, and a number of them, juniors in particular, have significant gold resources in the ground-but in both cases, their share prices remain weak.
Mexico has been a great place to mine, whether it's gold or silver. Are you as bullish on silver as you are on gold?
RM: Yes, I am, but I think you invest in these companies because of management, not because it's either gold or silver. While I believe that silver trades more as an industrial metal than a monetary metal, it trades in lock-step with gold. Consequently, when gold goes parabolic for the reasons we discussed earlier, silver will ride right along with it. They're both going to be fantastic.
TGR: You're apparently bullish on uranium, too.
RM: Absolutely. The Japanese are turning reactors back on because the country has realized that the economy can't survive without nuclear power. Germany is finding out that the decision to shut down its nuclear power plants was perhaps a knee-jerk reaction to what happened at Fukushima-a political decision made in the haste of the moment and it is bitterly regretting it. I think we'll see a reversal there.
And, you know, the Megatons-to-Megawatts program with Russia will end next year. The American government did sell off some high-grade nuclear material but that was more of a political gesture in response to lobbying efforts on behalf of one of the more powerful Congressional districts to keep 1,200 people working. Uranium actually has been a very good contrarian play for a while, and now I believe we'll see much higher uranium prices over the coming years.
TGR: So you're fond of nickel, bullish on uranium and enthusiastic about precious metals companies. Is part of the rationale behind your thinking the idea that emerging economies and developing nations will be implementing infrastructure programs that need more energy, more steel and more base metals? Would you say you're generally a commodities bull?
RM: I am a commodities bull, and although everything you just said is true, it goes deeper. It goes to the fact that a discovery is a discovery, and the market rewards discoveries. It rewards finding a resource and doubling it and tripling it. It rewards companies that go from near-term producer status to producers with cash flow. It rewards management, those who go to work for shareholders, build value and run solid junior companies. It rewards those that run ahead of the herd.
To me it doesn't matter whether we're in a bull market for commodities or a soft market, this kind of quality, this kind of shareholder value-building, will be rewarded. It always has been and I see nothing going on now in the market to change that. When you add in what we talked about with inflationary pressures and gold potentially as a Tier 1 asset, I see this as a perfect time to be looking at these companies with great management teams and projects that can really increase their share value at any time.
TGR: Excellent summary, Rick. Thank you so much for your time.
Richard (Rick) Mills is the founder, owner and president of Northern Venture Group, which owns aheadoftheherd.com, as well as publisher, editor and host of the website. Focusing on the junior resource sector, Mills has had articles appearing on more than 400 different websites including: The Wall Street Journal, Safe Haven, Market Oracle, USA Today, National Post, Stockhouse, LewRockwell, Pinnacle Digest, Uranium Miner, Beforeitsnews, Seeking Alpha, Montreal Gazette, Casey Research, 24hgold, Vancouver Sun, CBS News, Silver Bear Cafe, Infomine, Huffington Post, Mineweb, 321Gold, Kitco, Gold-Eagle, The Gold/Energy Reports, Calgary Herald, Resource Investor, Mining.com, Forbes, FN Arena, Uraniumseek, Financial Sense, Goldseek, Dallas News, VantageWire, Resource Clips and the Association of Mining Analysts.
Article published courtesy of The Gold Report - www.theaureport.com"